
What happened?
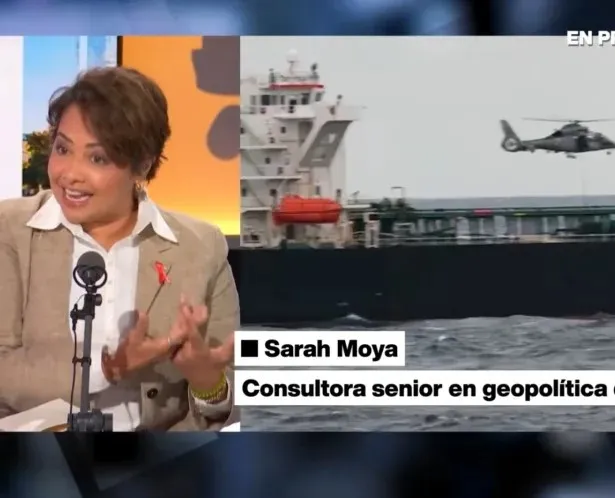
In 2025, pressure on energy maritime routes is intensifying: U.S.–Venezuela tensions triggering incidents in the Caribbean, soaring insurance premiums in the Red Sea, and growing congestion at the Panama Canal.
Why does it matter?
Nearly 80% of global hydrocarbon trade relies on maritime shipping. Europe is highly dependent on flows from West Africa, Latin America, and the Middle East. Each disruption translates into higher costs, unpredictable delays, and contractual risk for energy companies, insurers, and investors.
Implications for French and European companies
- Insurance: 15–25% increase in P&I premiums on specific routes.
- Logistics: need for alternative routes (Cape of Good Hope, Caribbean hubs).
- Compliance: higher exposure to sanctions and maritime compliance risks.
Receive our Alerts — Subscribe to CoreSight Strategies’ Geopolitical Flashs.